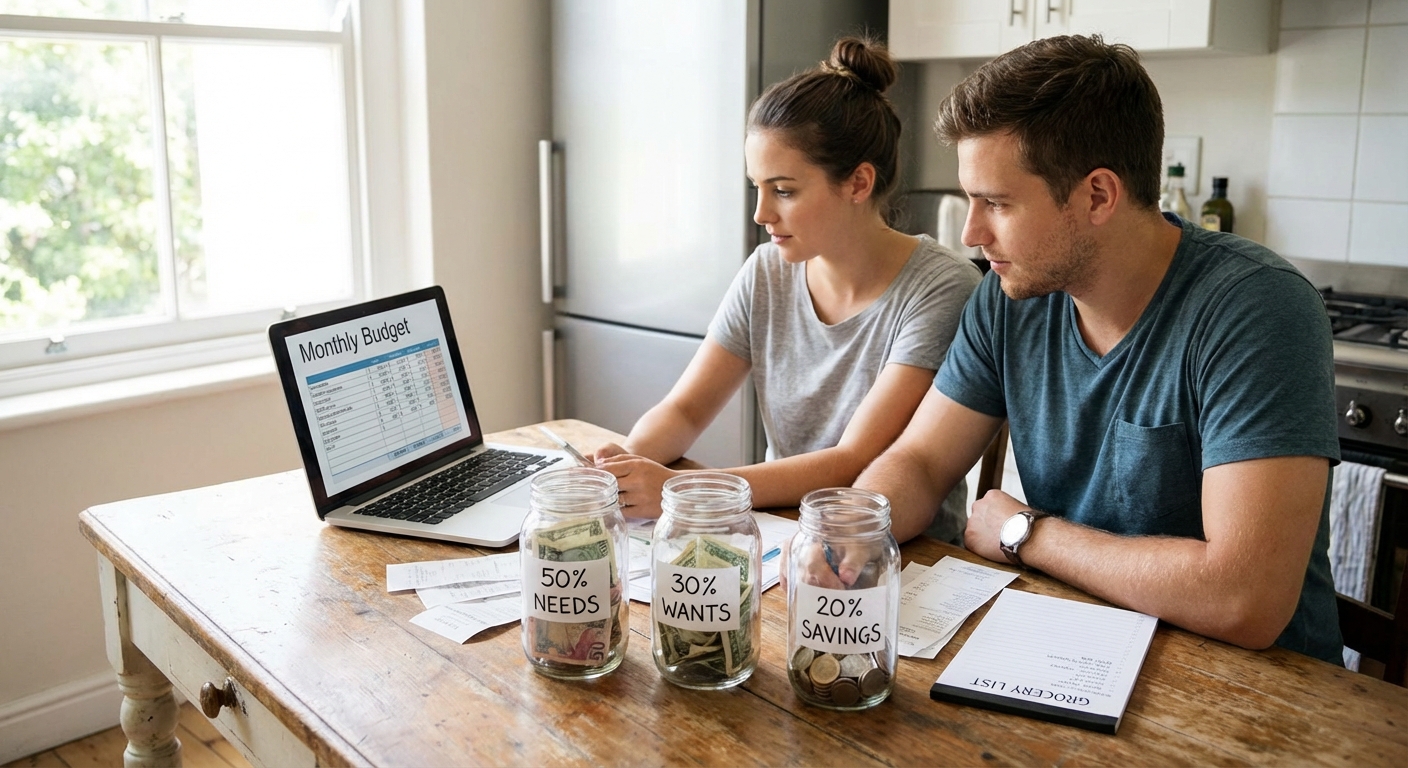
The 50/30/20 rule is a simple way to organize your money:
What Is the 50/30/20 Rule, Really?
- 50% of your take-home pay → Needs
- 30% → Wants
- 20% → Savings and debt payoff
“Take-home pay” means what lands in your bank account after taxes and other automatic deductions.
This rule is not a law. It’s a starting framework that can help you:
- See where your money is going
- Make room for saving
- Avoid all-or-nothing budgets
Let’s walk through how to use it in real life, even if your numbers aren’t “perfect.”
Step 1: Figure Out Your Monthly Take-Home Pay
If you’re paid regularly, do this once and reuse the number.
Example: Paid Every Two Weeks
- Look at your paycheck deposit: say it’s $1,350 each time.
- You’re paid every two weeks, so you receive 26 paychecks per year.
To estimate monthly income:
- $1,350 × 26 = $35,100 per year - $35,100 ÷ 12 ≈ $2,925/month
To keep it simple, round: $2,900/month.
If you’re paid monthly, just use your monthly number. If weekly, multiply by 52 and divide by 12.
Step 2: Turn That Into 50/30/20 Targets
Using our example of $2,900/month:
- Needs (50%): 0.50 × 2,900 = $1,450
- Wants (30%): 0.30 × 2,900 = $870
- Savings/Debt (20%): 0.20 × 2,900 = $580
- $1,450 for needs
- $870 for wants
- $580 for savings and extra debt payments
So your rough monthly “buckets” are:
You may not hit these numbers right away. That’s okay. We’ll adjust.
Step 3: Sort Your Spending Into Needs, Wants, and Savings/Debt
Use one recent month of transactions from your bank and credit cards.
What Counts as a Need
Needs keep your basic life running:
- Rent or mortgage
- Utilities (electricity, water, gas)
- Basic phone and internet
- Groceries (not luxury extras)
- Transportation to work (gas, bus pass, basic car costs)
- Minimum debt payments
- Insurance (health, car, renter’s, etc.)
What Counts as a Want
Wants are nice to have, but you could live without them if you had to:
- Eating out, takeout, coffee shops
- Streaming services and entertainment
- Vacations and trips
- Upgraded phone or cable plans
- Hobbies and shopping beyond essentials
What Counts as Savings/Debt
Money that builds your future or reduces what you owe:
- Emergency fund deposits
- Extra debt payments (beyond the minimums)
- Retirement contributions (if taken automatically, you can note them)
- Savings for goals (moving, car, etc.)
Step 4: Compare Your Real Life to the 50/30/20 Targets
Let’s use an example month for our $2,900 income.
Example Monthly Totals
- Needs: $1,750
- Wants: $700
- Savings/Debt: $150
Now compare to the guideline targets:
| Category | Guideline | Actual | Difference |
|---|---|---|---|
| Needs (50%) | $1,450 | $1,750 | +$300 |
| Wants (30%) | $870 | $700 | -$170 |
| Savings/Debt(20%) | $580 | $150 | -$430 |
What this tells you:
- Needs are taking more than the suggested 50% (not unusual with rent and inflation).
- Wants are under the guideline (you may already be cutting fun spending).
- Savings/debt is way under the 20% target.
This doesn’t mean you’re failing; it means the standard 50/30/20 split doesn’t fit your situation yet. We can still use it to find small changes.
Step 5: Create a “Real-Life” Version of the Rule
If your rent and essentials are high, you might use something like:
- 60% Needs
- 25% Wants
- 15% Savings/Debt
- Needs: 0.60 × 2,900 = $1,740
- Wants: 0.25 × 2,900 = $725
- Savings/Debt: 0.15 × 2,900 = $435
Using the same $2,900 income:
This is closer to your real numbers (Needs = $1,750; Wants = $700), but gives you a target to slowly move toward more savings.
You can adjust to any mix that fits your reality. The key idea:
- Keep needs from growing too big,
- Let yourself have some wants,
- Always leave something for savings or extra debt payments.
Step 6: Make 2–3 Concrete Changes to Free Up Savings
Instead of trying to jump straight to 20% savings, focus on simple moves.
1) Set a Starting Savings Percentage
If you’re currently saving $150/month, that’s about 5% of $2,900.
Aim for, say, 8% for the next few months:
0.08 × 2,900 = $232/month.
That’s an additional $82/month you need to find.
2) Look for High-Impact Tweaks
Use your Wants and Needs lists to find areas to nudge.
Possible changes:
- Cut one $12.99 streaming service → ~$13/month
- Reduce takeout by one meal/week, saving $10 each → $40/month
- Switch to generic groceries for a few items → $15/month
- Call internet provider to negotiate or downgrade plan → $15/month
Approx total: $83/month.
You’ve just freed the $82/month you needed to hit that 8% target.
Step 7: Set Up Your Savings So It Actually Happens
Having a target is nice. Making it automatic is better.
Action Steps
- Open a separate savings account if you don’t have one.
- Take your new monthly savings target (for example, $232).
Decide how often you’ll transfer:
- If paid biweekly: $232 ÷ 2 ≈ $116 per paycheck. 4. Set up an automatic transfer from checking to savings every payday.
Now, your version of the 50/30/20 rule is happening behind the scenes.
If that number feels scary, start with half and increase later.
Step 8: Use a Simple Check-In Once a Month
You don’t have to track every penny forever. But a monthly 15-minute check-in helps keep you on track.
Each month, quickly total:
- Needs spending
- Wants spending
- Savings/debt
Compare to your current targets, not the textbook 50/30/20.
Example: You’re aiming for 60/25/15, and you see this:
- Needs: 62%
- Wants: 24%
- Savings/Debt: 14%
You’re close enough. Maybe aim to trim a little from Needs (if possible) or move $10–$20 from Wants to Savings next month.
Step 9: Adjust as Your Life Changes
Your 50/30/20 (or 60/25/15) split is not permanent.
Major changes that should trigger a review:
- New job or raise
- Move to a more or less expensive area
- Debt paid off
- New recurring bill (like a car or child care)
- Increase savings first before expanding lifestyle.
- Extra $300/month
- Decide to put at least half ($150) toward savings/debt
- Use the rest for Wants or to make Needs more comfortable.
When your income rises, try this rule:
For example, if your monthly take-home pay increases from $2,900 to $3,200:
What If You Can’t Reach 20% Savings Right Now?
That’s okay.
If your rent is high, you’re supporting family, or you’re dealing with debt, your numbers may look more like:
- 70% Needs
- 20% Wants
- 10% Savings/Debt
- Not letting Wants grow bigger than they are now.
- Slowly shifting some Needs (like expensive plans) to cheaper options.
- Growing savings by 1–2% at a time when possible.
At this stage, focus on:
Even 5–10% savings is far better than 0%. Small wins matter.
Final Thoughts: Use the Rule as a Guide, Not a Judge
The 50/30/20 rule is useful because it gives you
- A simple structure
- Clear targets
- A way to see where your money is going
But it’s not a test you pass or fail.
Use it to:
- Understand your current spending
- Decide your own personalized percentages
- Set realistic savings targets
- Adjust over time as your situation improves
You don’t need perfect ratios to make progress. If you can move from saving 0% to 5%, then 5% to 8%, then 8% to 10%, you’re already changing your financial future in a big way—one percent at a time.